
window.dataLayer = window.dataLayer || []; function gtag(){dataLayer.push(arguments);} gtag('js', new Date()); gtag('config', 'UA-206511945-1');
Search
Categories
Uncategorized

How to Create a Salon Budget for Monthly Costs and Cash Flow

A salon’s monthly costs depend on its size, but they shouldn’t be a mystery. To learn how to create a salon budget, list recurring expenses, estimate variable costs, and compare the total with expected income.

Rent, payroll, supplies, and quiet periods can all make cash harder to predict. A clear budget shows what the salon needs to earn, helps you plan for bills, and supports more confident spending decisions.

Learn how to track expenses, build monthly and quarterly forecasts, plan for salon space and equipment, and protect cash flow during slower periods. You’ll also see how to review your numbers and adjust the plan as costs or income change.

Key Takeaways

  • Sort expenses into fixed and variable costs, then review what share of spending each category takes.
  • Build forecasts around your salon model, staffing, rent, supplies, and expected income rather than relying on a one-size-fits-all budget.
  • For a suite or booth, account for rent, startup deposits, supplies, and equipment before setting your monthly spending plan.
  • Prioritize equipment that supports services clients use regularly, and compare its ongoing costs with the revenue it could bring in.
  • Plan for slower periods by setting cash aside and scheduling bill payments around expected income.

1. Should I Track Salon Expenses Using a Spreadsheet?

Yes. A spreadsheet gives you one place to track income, expenses, and performance, then compare actual spending with your plan. Include wages and related staff costs, rent, insurance, supplies, and marketing. Record transactions monthly to see what the salon earns, spends, and where costs are changing.

Create a separate row for each expense, with columns for the date, category, amount, payment method, and a short note. Track income in a separate section, grouped by service, retail sales, or other revenue. For example, record a colour service as service income and the product used as a supply expense. This keeps income and spending distinct while showing how each service contributes to results.

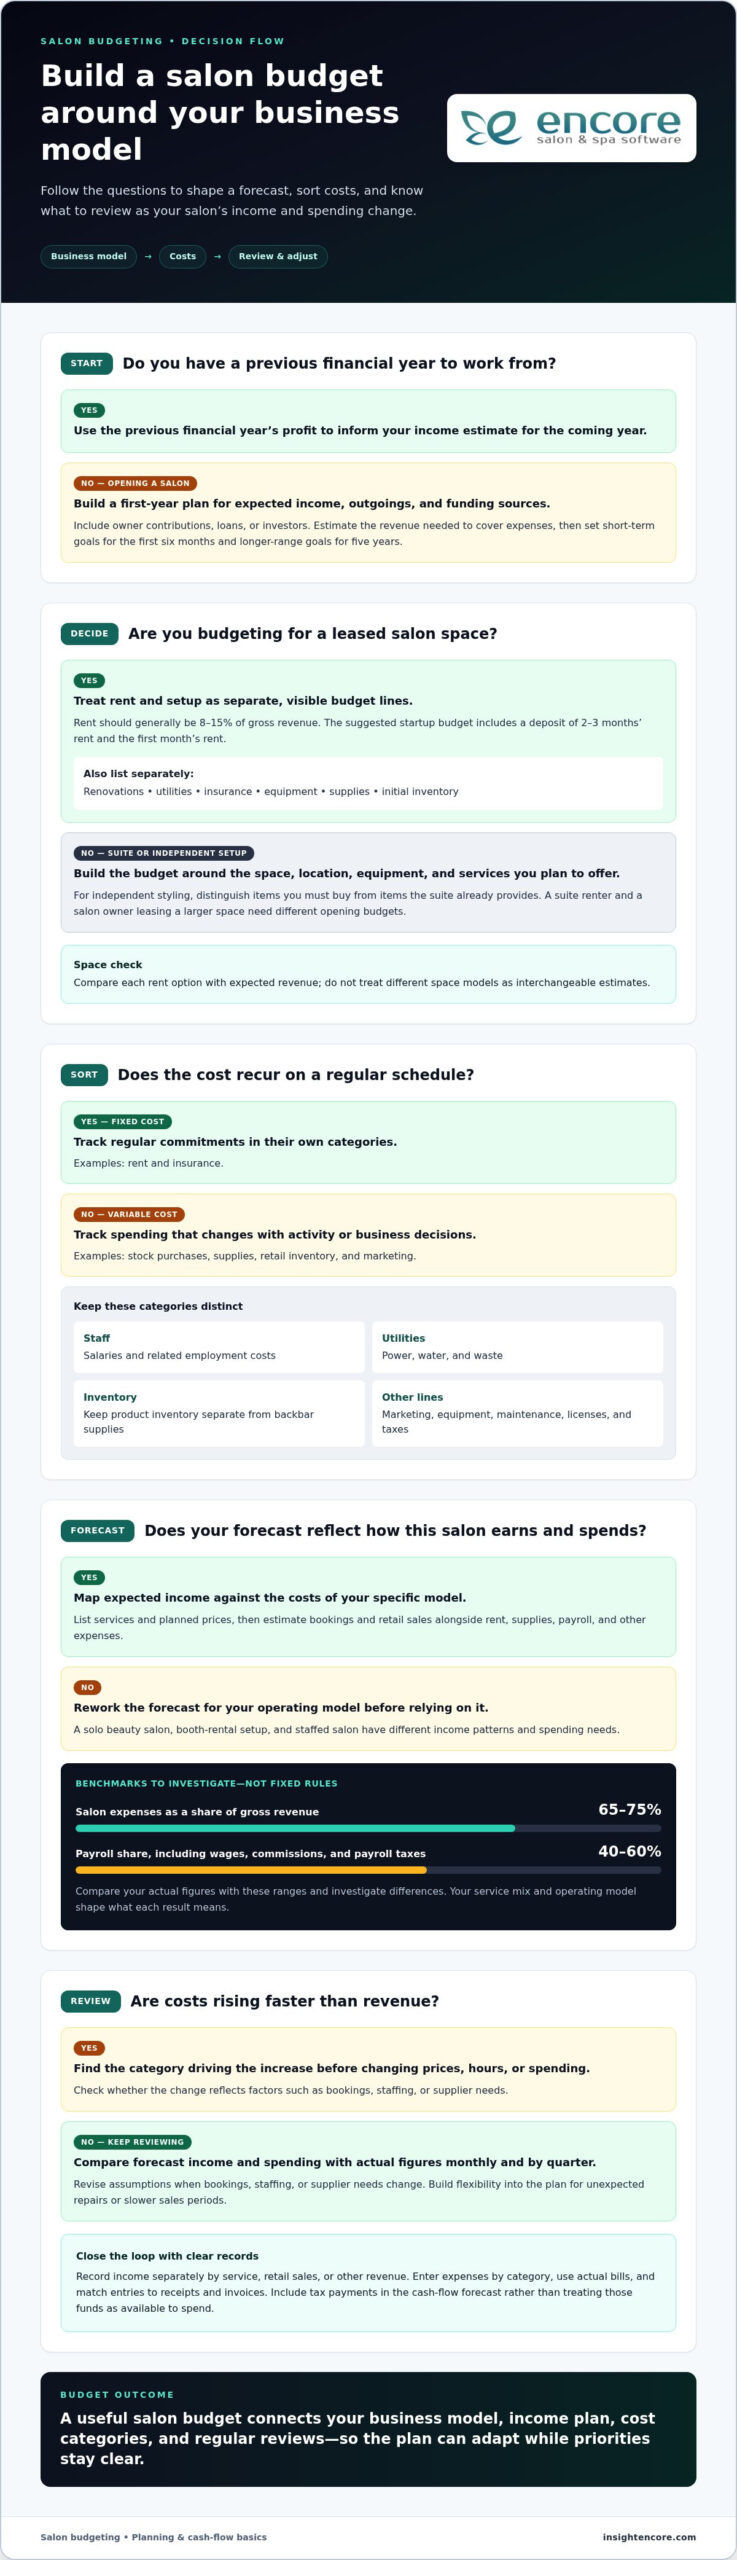
Classify costs as fixed or variable. Fixed expenses generally recur on a regular schedule, such as rent and insurance. Variable expenses change with activity or purchasing decisions, including stock and marketing. Give wages and related staff costs their own category, as they can include different types of compensation. Avoid combining unlike costs: separate product inventory from backbar supplies so you can see which area needs attention.

  • Fixed: Rent, insurance, and other regular bills.
  • Variable: Stock purchases and marketing spend.
  • Staff: Salaries and related employment costs.
  • Utilities: Track power, water, and waste separately.

Use actual bills rather than estimates. These are example figures, not standard salon rates; your entries should match your invoices and payment records. Save receipts and invoices by month, then match each spreadsheet entry to its supporting record. This makes duplicate charges and missing bills easier to spot.

At month-end, total each category and calculate its share of total expenses. Compare the results with the previous month and note the reason for any meaningful change, such as a larger stock order or a new staff cost. Review income alongside expenses rather than judging performance by sales alone. This monthly check can reveal whether higher spending supports revenue or simply reduces what remains.

Keep the spreadsheet manageable: use consistent category names, enter transactions regularly, and preserve original records. A simple sheet works well when you keep it up to date. As salon activity grows, the same categories and monthly totals provide a clear structure for refining your budget and tracking performance.

2. How do you create a solid financial plan and budget for your hair or beauty salon?

Build the plan around your business model, expected revenue, and costs. A solo beauty salon, a booth-rental setup, and a staffed salon have different income patterns and spending needs. List your services and planned prices, then map expected bookings and retail sales against rent, supplies, payroll, and other expenses. This makes revenue goals practical rather than guesswork.

For a yearly forecast, use the previous financial year’s profit to inform your income estimate for the coming year. If you’re opening a salon, prepare a first-year plan covering expected income, outgoings, and funding sources such as owner contributions, loans, or investors. Set milestones: estimate the revenue needed to cover expenses, then create short-term goals for the first six months and longer-range goals for five years.

Use percentage benchmarks as prompts for review, not fixed rules for every business. Salon expenses commonly total 65 to 75 percent of gross revenue, while payroll, including wages, commissions, and payroll taxes, may take 40 to 60 percent. Compare your actual figures with these ranges and investigate differences. For example, a rising payroll share could reflect staffing changes, lower bookings, or both. Your own service mix and operating model shape the meaning of each result.

Keep fixed and variable costs visible in the plan. Rent and insurance are recurring commitments; supplies, retail inventory, and marketing can change with activity or business decisions. Give marketing, equipment, and maintenance separate categories, and connect each planned expense to a purpose. For example, record a campaign’s cost alongside the bookings or sales it supports. For equipment, consider purchase or financing costs, upkeep, and the services it enables.

Put licenses, taxes, and local operating requirements in separate budget lines, since costs and timing depend on location and business structure. Keep supporting records with each entry, and include tax payments in the cash-flow forecast rather than treating those funds as available to spend.

Review the budget monthly and organize results by month and quarter. Compare forecast income and spending with actual figures, then revise assumptions when bookings, staffing, or supplier needs change. Build flexibility into the plan so an unexpected repair or slower sales period doesn’t derail a key goal. If costs rise faster than revenue, identify the category driving the increase before adjusting prices, hours, or spending. A useful financial plan can adapt while keeping the salon’s priorities clear.

3. Salon suite and independent renter costs

A suite renter and a salon owner leasing a larger space need different opening budgets. Treat them as separate business models, not interchangeable estimates: your figures depend on the space, location, equipment, and services you plan to offer.

Rent is often the largest commitment. Compare each option with expected revenue; salon rent should generally be 8–15% of gross revenue.

Before opening, list the costs required to occupy and operate the space. For a leased salon, the suggested startup budget includes a deposit of 2–3 months’ rent and the first month’s rent. Add renovations, utilities, insurance, equipment, supplies, and initial inventory as separate lines. For independent styling, distinguish items you must buy from items the suite already provides. This prevents a low weekly rent from disguising additional setup spending.

Base the plan on your operating model. A booth renter may have fewer shared-space obligations than a salon owner, but still needs funds for tools, products, and client-facing operations. Estimate monthly outgoings, then compare them with realistic service capacity and expected bookings. If rent takes too much of projected gross revenue, consider whether a smaller space, fewer services, or a different location would make the plan more workable.

Salon owners can lower upfront costs by prioritizing what clients need for everyday services. Start with core retail inventory displayed neatly on simple shelves, then upgrade fixtures as sales grow. Open shelves, ready-made cabinets, or wall racks can replace custom cabinetry at launch. Choose practical roller shades or basic blinds instead of expensive window treatments, and postpone high-end options until the business is established.

Build a startup worksheet with columns for one-time purchases, recurring costs, and each bill’s due month. Include a separate cash reserve for opening expenses that come before regular bookings begin. Review the numbers whenever a lease, renovation, or equipment decision changes. A smaller initial setup can protect cash, but should still support safe, efficient styling and the services you intend to offer.
How to Create a Salon Budget for Monthly Costs and Cash Flow

4. Adding equipment to expand services and revenue

Equipment can create a new revenue stream, but every purchase needs a clear role in your plan. Before adding a facial steamer, nail table, or styling station, identify which service it supports and who will use it. Estimate how often clients might book that service, whether existing staff can provide it, and what supplies or upkeep it requires. Connect each purchase to a specific business opportunity.

Start with the full cost, not just the purchase price. Include financing payments, delivery, setup, maintenance, supplies, and any change in insurance costs related to the equipment. The actual payment depends on the equipment and financing terms, so add the expected amount to your cash-flow forecast before committing.

Next, set a revenue target for the equipment. Estimate how many additional appointments it could support in a typical month, then calculate how much revenue those bookings need to generate to cover ongoing costs. Use your own service prices and realistic appointment capacity. For example, a salon adding a treatment service can track bookings, supply use, and income separately to see whether the new offering contributes to profit.

Prioritize equipment that clients and stylists will use regularly. A core item supporting several appointments may deserve attention before a specialty purchase with limited use. You can delay upgrades to furnishings or tools that don’t affect current services. This staged approach preserves cash for existing expenses and lets you assess whether demand supports a larger investment.

Keep revenue streams distinct in your records. Separate service income from retail sales, booth or suite income, and gift card sales where applicable. Track the service or revenue stream connected to each equipment purchase. This helps you compare performance over time and identify whether growth comes from the new service, stronger bookings elsewhere, or other sales.

Review performance monthly after the equipment is in use. Compare actual appointments and related revenue with your target, then include supplies, repairs, loan payments, and relevant insurance costs. If usage stays low, consider whether scheduling, staff training, or client awareness is limiting bookings before buying more equipment. A clear review helps you base the next purchase on performance, not excitement alone.

5. Reasons salons and spas need budgets and cash-flow plans

A budget shows whether the salon can cover its costs; a cash-flow forecast shows when money arrives and bills are due. To build one, list expected service, retail, and other income by month, then add payment dates for rent, payroll, suppliers, and loans. Set aside a cash reserve from available funds to cover quiet periods or unexpected costs, rather than relying on sales that haven’t arrived.

Timing matters. A salon may be busy around Christmas, then see quieter bookings in January. If rent, wages, and supplier invoices are still due during that slower month, strong holiday sales can disappear quickly. Forecast income and payments across the calendar, not only as monthly totals. This helps you spot a shortfall before a bill is due and decide whether optional spending can wait.

Opening a salon also creates a gap between startup costs and steady customer income. Include deposits, initial stock, equipment payments, and wages in the forecast alongside anticipated bookings. Record when each expense must be paid and when clients are expected to pay. For retail, account for the cash spent on products before projecting income from their sale. Separating these dates makes your working cash needs easier to see.

Use the forecast to plan bill payments. Pay invoices by their due dates, and don’t treat future bookings as cash already available. If income is lower than expected, review upcoming expenses and identify purchases that can wait without disrupting services. Keep essential costs separate from optional upgrades so decisions reflect the actual cash position, not just a sales target.

A useful cash-flow review compares planned and actual deposits, sales, and payments. Update the forecast when bookings shift, a supplier invoice changes, or an equipment repair comes due. Note the reason for each difference. For example, a slower January might mean postponing a retail order, while stronger-than-expected service sales could support replenishing popular products. This connects your reserve to decisions instead of leaving it as an unexplained balance.

Software can help organize appointments, sales, and expenses as part of a regular operating routine, but the forecast still depends on accurate entries and consistent review. Set a monthly review to compare expected cash with the account balance and invoices due. Then adjust planned purchases or reserve contributions using the updated figures. A profitable month doesn’t automatically mean cash will be available when the next bill arrives.

[Explore salon cash-flow tools](https://insightencore.com/try-encore-now/)

Encore Salon & Spa Software: Encore Salon Software

Encore Salon & Spa Software offers Encore Salon Software to help manage salon operations. When appointment activity, sales, and stock are spread across separate records, a salon management platform can bring those workflows together and make information easier to use in budget reviews. Online booking helps manage appointments, while point-of-sale transactions and inventory management support tracking sales and product movement.

Use these operating records in your financial reviews: compare service and retail activity with budgeted expenses, then adjust purchasing or forecasts as needed. Encore also offers Encore Spa Software, Chair/Booth Renter Software, and Tattoo Studio Software for other business models.

Contact Encore Salon & Spa Software to learn more about Encore Salon Software.

Make your next budget decision with confidence

A salon budget works best as a living decision tool, not a document you file away after opening. As your services, team, or booking patterns change, use each review to decide what needs attention next. Learning how to create a salon budget helps you make those choices from clear records rather than guesswork.

Choose one manageable next step today: update a category, review an upcoming purchase, or schedule your next financial check-in. If appointment and sales information is difficult to organize alongside those decisions, Encore Salon & Spa Software offers Encore Salon Software, Encore Spa Software, and Chair/Booth Renter Software for different business needs.

[Contact Encore Salon & Spa Software](https://insightencore.com/try-encore-now/)

With a clear process and regular reviews, you can approach each new business decision with greater clarity.

Frequently Asked Questions

How much does it cost to run a hair salon per month?

A full-service salon’s costs depend on staffing, rent, services, and purchasing needs, so a smaller salon will have a different cost profile. Estimate your own total by adding regular bills, expected payroll, supply orders, and other operating expenses, then compare the result with forecast revenue.

What Does a Monthly Salon Budget Look Like?

A monthly salon budget brings expected income, planned spending, and payment timing together. List service and retail income separately, then group costs under rent, payroll, utilities, supplies, equipment, and marketing. Add bill due dates and notes about changes, such as an unusually large product order. Reviewing categories during the month can help you spot where actual spending is moving away from plan.

How do you create a solid financial plan and budget for your hair or beauty salon?

Start with your business model, services, and expected income sources. Use sales records if the salon is operating, or estimate opening revenue from planned appointments and service prices. To learn how to create a salon budget, match income estimates against costs and payment dates, then set revenue milestones. Review actual results regularly and revise assumptions when bookings, staffing, or purchasing patterns change.

Should I Track Salon Expenses Using a Spreadsheet?

Yes, a spreadsheet can organize salon spending and compare actual costs with planned amounts. Create sections for transactions, monthly totals, and budget-versus-actual results. Use consistent categories and formulas to total expenses, and keep supplier invoices separate from equipment purchases. Filtering by month can reveal recurring charges or unusual entries. To put a salon budget into practice, use these comparisons to identify categories that need closer review.

What Are Fixed Expenses?

Fixed expenses are recurring business costs that generally remain stable over a set period, even when bookings change. Rent and insurance are common examples; regular software subscriptions or scheduled loan payments may also fit. Record each cost with its due date and payment amount. When a contract or payment schedule changes, update the entry so your forecast reflects the salon’s current commitments.

What Are Variable Expenses?

Variable expenses change with business activity, customer demand, or purchasing decisions. A salon may order more colour products during a busy booking period, while retail stock needs can shift with customer purchases. Marketing costs may also vary by campaign. Track each cost separately and note its purpose. This context helps you distinguish demand-related changes from optional spending when reviewing monthly results.

What makes a salon profitable?

A salon is profitable when revenue exceeds total expenses over the period being measured. The remaining amount is profit, which differs from cash currently available because payments and income may arrive at different times. Most salons have a net profit margin of 8 to 15 percent. Compare service and retail performance with related costs, then assess whether additional spending contributes to income or reduces what remains.

What are typical monthly operating costs for a salon?

Common operating costs include rent, payroll, utilities, insurance, supplies, retail inventory, marketing, software, and equipment upkeep. Keep these categories separate in your records. A single expense total won’t show whether rent, labour, or stock is driving a change in monthly spending.

Disclaimer

This article is general in nature and may contain errors, please verify all claims with your sales rep
Categories
Uncategorized

Salon Cash Flow Management: 2026 Financial Guide

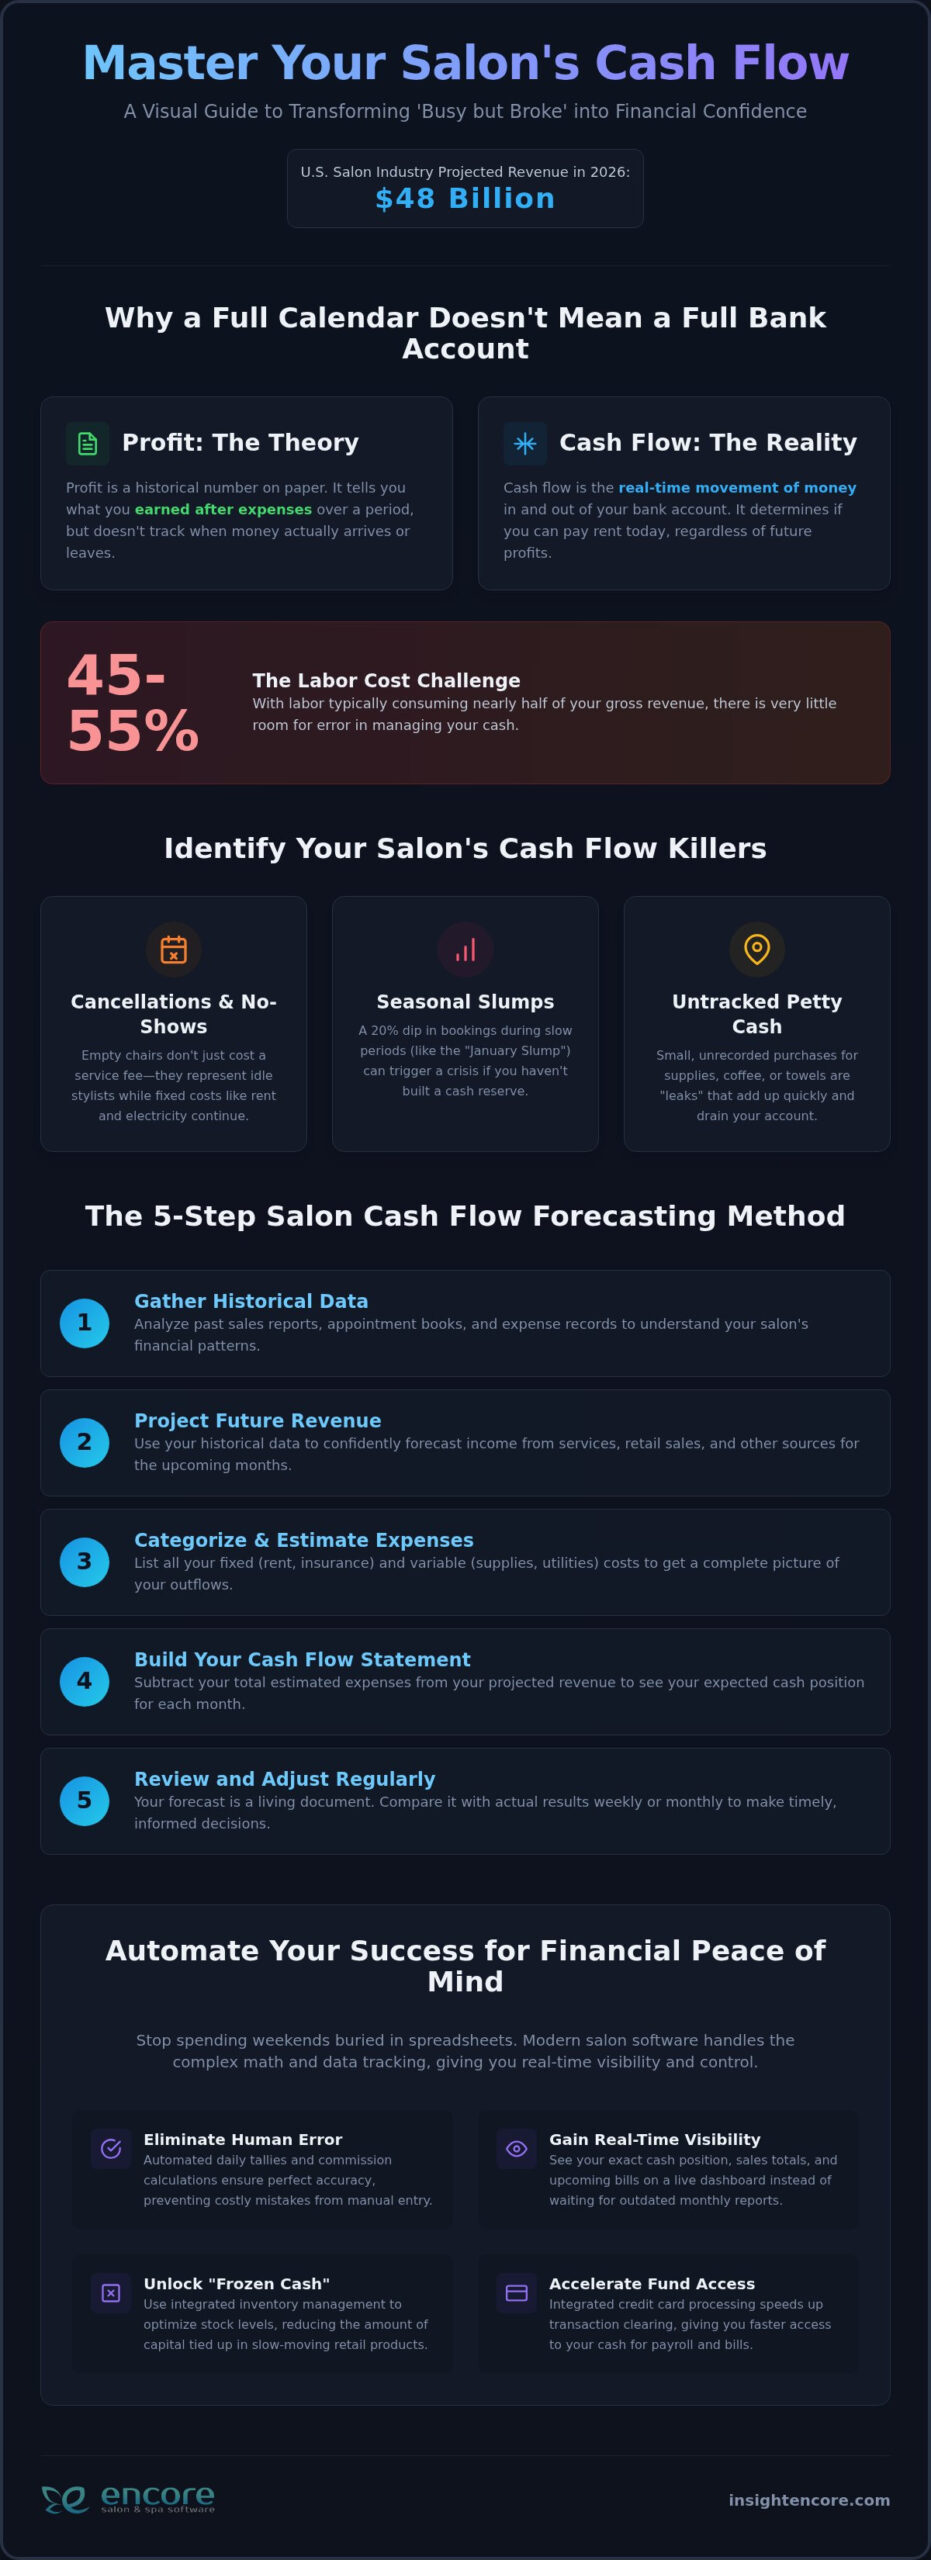
With the U.S. salon industry projected to generate $48 billion in revenue in 2026, why does it feel like your bank account is often running on empty? It’s a common frustration to see every chair full yet still worry about covering the next lease payment. You aren’t alone in feeling the sting of unpredictable slow seasons or the headache of tying up too much capital in retail stock that just won’t move. Learning how to manage salon cash flow effectively is the vital shift that transforms a talented artist into a confident, relaxed business owner.

We understand that you started this journey to create beauty, not to spend your weekends buried in complex spreadsheets. It’s exhausting to manually calculate staff commissions or wonder exactly where your profit disappeared. This guide is your roadmap to financial clarity. We will provide a step-by-step framework to stabilize your monthly income and automate the “math” that currently causes so much stress. You’re about to discover how to gain a clear understanding of your finances and ensure your business thrives in 2026 with systems that work as hard as you do.

Key Takeaways

  • Understand why a fully booked calendar doesn’t always mean a healthy bank account by mastering the difference between profit and real-time cash flow.
  • Stop “leaky” finances by categorizing fixed and variable expenses and implementing a simple daily reconciliation routine that keeps you in control.
  • Unlock “frozen cash” by optimizing your inventory levels and aligning staff schedules with your most productive hours to reduce unnecessary overhead.
  • Follow a proven five-step method on how to manage salon cash flow effectively by using historical data to project future revenue with confidence.
  • Learn how automated tools like Encore Salon Software handle complex math and data tracking for you, letting you focus on your clients instead of spreadsheets.

Profit vs. Cash Flow: Why Your Salon Can Be Busy but Broke

It’s a frustrating paradox. Your stylists are booked solid and you might even hit the industry average revenue of $245,000. Yet, when you look at your bank balance on Friday, there’s barely enough to cover the rent. This is the “Busy but Broke” trap. It happens because profit is just a theoretical number on paper, while cash flow is the cold, hard reality of your bank account. To understand what cash flow is, you have to look at the timing of every transaction. Profit tells you what you earned after expenses, but cash flow tracks exactly when that money arrives and when it leaves.

In a salon, managing this is uniquely complex. You’re balancing service revenue, which is immediate, with retail stock that might sit on a shelf for months. With labor costs typically eating up 45% to 55% of your gross revenue, there is very little room for error. You have to track three main types of movement:

  • Operating Cash Flow: The daily money from haircuts, colors, and product sales.
  • Investing Cash Flow: Money spent on long-term assets, like new salon chairs or high-end equipment.
  • Financing Cash Flow: Cash used for loans or business debt.

Learning how to manage salon cash flow effectively starts with recognizing that timing is everything. If your expenses hit on the 1st but your big color appointments aren’t until the 15th, you have a cash flow problem, even if you are profitable by the end of the month.

Common Cash Flow Killers in the Beauty Industry

Small leaks can sink a big ship. Last-minute cancellations and no-shows are the most immediate thieves. They don’t just cost you a service fee; they leave a stylist idle while your fixed costs, like electricity and rent, keep ticking. Then there’s the “January Slump.” If you haven’t built a reserve during the busy holiday season, a 20% dip in bookings can feel like a crisis. Finally, watch your petty cash. Those emergency trips to the store for extra towels or coffee pods add up quickly if they aren’t tracked daily.

The Role of Visibility in Financial Peace of Mind

You can’t fix what you can’t see. Many owners wait for a quarterly report from their accountant, but that’s like looking in the rearview mirror while driving. By the time you see a problem, it’s three months old. Real-time data gives you the power to make decisions today. Instead of relying on a gut feeling that the salon is doing well, you need to know your exact totals every evening. Automation is the key. It removes human error from daily tallies and ensures that your commission math is perfect. When you use integrated management features, the stress of the unknown disappears, replaced by a feeling of organized control.

Building a Foundation: Tracking Income and Expenses with Precision

Running a salon is deeply personal. Every dollar represents a client served or a product sold. To keep that money where it belongs, you need a crystal-clear map of your outflows. This starts with separating your fixed costs from your variable ones. Your fixed costs, like rent and insurance, are the anchors that stay the same every month. Variable costs, such as backbar supplies and utilities, are more fluid. Tracking these categories separately is how to manage salon cash flow effectively because it stops small, variable leaks before they become floods.

Daily reconciliation is your best defense against “leaky” cash flow. It’s tempting to wait until the end of the week, but small errors in manual entry or untracked petty cash purchases add up quickly. By spending ten minutes each evening balancing your till, you ensure your records match your bank account. This habit creates a reliable foundation for your morning check-in. A simple cash flow dashboard allows you to see your current balance and upcoming bills in just five minutes, giving you the confidence to start your day with a clear head.

Automating Revenue Tracking with POS Integration

Manual data entry is a magnet for human error. When you use integrated credit card processing, your sales data flows directly into your management system without you lifting a finger. This automation captures every detail, including digital tips and service add-ons that might otherwise slip through the cracks. It also speeds up fund availability. Instead of waiting days for transactions to clear, integrated systems often provide faster access to your cash, which is vital for meeting immediate payroll needs.

Managing Outflows: The ‘Envelope Method’ for the Digital Age

The “Envelope Method” isn’t just for physical cash; it’s a powerful digital strategy too. By allocating specific percentages of your daily revenue to separate “envelopes” or accounts, you ensure you’re never scrambling for tax or payroll money. For example, you might set aside 15 percent for taxes and 50 percent for labor costs immediately. This proactive approach allows you to implement strategies to strengthen your financial stability during the quieter seasons.

Modern software can even flag your account when variable expenses, like your monthly color order, exceed your set budget. There is a massive psychological benefit to seeing “saved” cash sitting in a dedicated account for future bills. It replaces the panic of the unknown with a sense of organized control. If you’re ready to see how simple this tracking can be, you can explore our all-in-one management tools today.

Optimizing Your Two Largest Outflows: Inventory and Labor

Inventory and labor are the two heaviest weights on your balance sheet. If they aren’t balanced perfectly, they can pull your entire business down. Many owners see a shelf full of products and feel a sense of security, but that’s a mistake. Think of your backbar and retail shelves as “frozen cash.” Every bottle sitting there is money that isn’t available to pay your team or your rent. Understanding the relationship between these two expenses is the next step in learning how to manage salon cash flow effectively.

Labor is your highest expense, typically accounting for 45% to 55% of gross revenue in 2026. If you have three stylists standing around during a Tuesday morning dead zone, you’re paying to keep the lights on for no return. This is especially critical for specialized businesses like tattoo studios or booth rental spaces. These “mini-cash flows” require precision to ensure the house stays profitable while the artists thrive. Commission structures also impact your weekly cash availability. If you pay out commissions before your credit card deposits fully clear, you create a temporary cash crunch that can be avoided with better timing.

Smart Inventory Management: Freeing Up Your Capital

Stop guessing what you need to order. You can implement “Par Levels” to trigger orders only when you hit a specific minimum. This ensures you aren’t overbuying “Dust-Gatherers,” which are products that haven’t moved in 90 days. When you use Encore’s inventory management, this process becomes automatic. The system tracks every ounce used in the backbar and every bottle sold at retail, keeping your capital fluid instead of trapped on a shelf.

Aligning Staff Performance with Financial Health

A busy salon isn’t always a productive one. You need to track your salon staff utilization rate to see if your team’s time is being used efficiently. If utilization is low, it’s time to adjust your scheduling or focus on automated marketing to fill those gaps. Automated commission calculations also prevent “human error” overages that can quietly drain your accounts. By incentivizing your staff to focus on high-margin services like color corrections or scalp treatments, you increase the amount of cash staying in the business after labor costs are paid.

Salon Cash Flow Management: 2026 Financial Guide

The 5-Step 2026 Salon Cash Flow Forecasting Method

Forecasting is your financial weather report. It tells you when to carry an umbrella and when to soak up the sun. If you’re tired of being surprised by a low bank balance, learning how to manage salon cash flow effectively requires a proactive look at the months ahead. This isn’t about being a math genius; it’s about using your existing data to make informed decisions. This 5-step method for 2026 simplifies the process so you can plan with total confidence. To take your planning even further, a dedicated salon financial forecasting template can give you a plug-and-play framework that moves you from gut feelings to a clear, data-backed strategy for the year ahead.

  • Step 1: Gather 12 months of historical data. This shows you the natural rhythm and seasonal cycles of your business.
  • Step 2: Project future revenue. Use your current booking trends and staff levels to estimate what’s coming in the next quarter.
  • Step 3: List known upcoming expenses. Include everything from license renewals to planned equipment upgrades and lease increases.
  • Step 4: Factor in seasonal peaks and valleys. Plan for the holiday rush and the January slump at the same time.
  • Step 5: Adjust your strategy. This is where you decide how to manage salon cash flow effectively by cutting unnecessary costs or launching a new marketing campaign.

Projecting Revenue in a Subscription and Service Economy

The beauty industry is leaning heavily into recurring revenue models. If you offer memberships, include that guaranteed income in your projections. It’s also helpful to estimate the lifetime value of a new client. A one-time visitor is a win, but a client who returns every six weeks is a financial pillar for your business. Don’t forget about gift card sales. These are fantastic immediate cash injections that can help bridge a gap during a slow week. Just remember to track these as liabilities so you’re ready when the client returns to redeem them later in the year.

Building the ‘Peace of Mind’ Cash Reserve

Every salon owner deserves to sleep soundly at night. We recommend following the “Rule of Three” as a core part of your financial strategy. Your goal is to have three months of operating expenses sitting in a separate business savings account. You don’t need to find this money all at once. Build this reserve incrementally by setting aside a small percentage of your weekly profit, perhaps just 2 or 3 percent. This habit ensures your business remains stable without hurting your daily operations or your ability to pay your team. This emergency fund is your shield against the unexpected, like a sudden equipment failure or a change in local regulations. Having this cushion allows you to lead your team with a sense of calm and control. Pairing this reserve-building habit with a thorough salon business health checklist gives you a complete picture of your studio’s financial and operational readiness for the year ahead.

Start your financial transformation today

Leveraging Encore Salon Software to Automate Your Success

You didn’t open your doors to become a full-time bookkeeper. You’re an artist, a mentor, and a leader. While the financial framework we’ve discussed is vital, you shouldn’t have to spend your Sunday nights manually entering data into a spreadsheet. This is where Encore acts as your friendly mentor, handling the heavy lifting of data tracking so you can stay focused on your team and your clients. Shifting your focus to how to manage salon cash flow effectively through automation is the single most impactful change you can make for your business in 2026.

One of the biggest mistakes owners make is “Frankenstein-ing” their business by using five different apps that don’t talk to each other. When your booking system, inventory tracker, and credit card processor all live under one roof, you eliminate the data gaps that lead to financial surprises. For specialized businesses like tattoo studios or niche wellness centers, this level of integration is even more critical. You need a system that understands the specific nuances of your craft, from tracking booth rental fees to managing high-ticket service deposits.

Integrated Tools That Drive Immediate Inflows

Waiting for money to arrive is the hardest part of the “Busy but Broke” cycle. Encore helps you break that cycle with tools designed to secure your income before the client even walks in. By setting automated deposit requirements for high-ticket services like extensions or complex color work, you protect your time and your cash. If your calendar shows a gap, you can use built-in marketing automation to send targeted offers to your most loyal clients, filling those empty chairs instantly. Best of all, our simplified financial reporting translates complex numbers into clear, actionable insights that you can actually understand at a glance.

Taking the Next Step Toward Financial Freedom

Upgrading your management system is about more than just better math; it’s an investment in your mental health. The constant low-level stress of “not knowing” is what leads to burnout. Transitioning from a state of surviving to thriving requires the visibility that only professional software can provide. You don’t have to be an accountant to run a highly profitable business. You just need the right partner to handle the details. Encore is the ultimate answer to how to manage salon cash flow effectively without the daily headache of manual tracking.

Explore Encore Salon Software features

Transforming Your Financial Future

Mastering the art of financial management is the bridge between being a busy stylist and becoming a thriving business owner. You’ve learned that profit on paper doesn’t always match the cash in your hand, and that visibility is your greatest tool for stability. By optimizing your inventory and aligning your labor costs with actual productivity, you’re already ahead of the curve. Learning how to manage salon cash flow effectively is a journey that replaces daily stress with organized control.

Since 1991, we’ve helped salons, spas, and tattoo studios across the globe simplify their operations. Our all-in-one management platform handles the complex data lifting, from integrated inventory tracking to automated payroll calculations. You don’t have to navigate these financial hurdles alone. With the right systems in place, you can focus on the creative work you love while your business grows with confidence.

Take Control of Your Salon's Finances with Encore Salon Software

Your path to a predictable monthly income and a thriving salon starts today. We’re here to guide you every step of the way toward the financial freedom you deserve. You’ve got the talent; now you have the framework to match it.

Frequently Asked Questions

What is the difference between profit and cash flow in a salon?

Profit is the surplus left over after all expenses are subtracted on paper, while cash flow is the actual timing of money entering and leaving your bank account. A salon can be profitable but still run out of cash if bills are due before client payments arrive. Understanding this distinction is key to learning how to manage salon cash flow effectively. It ensures you have liquid funds for daily operations regardless of your paper revenue.

How much cash reserve should a small salon ideally have?

A small salon should ideally aim for a cash reserve that covers at least three months of operating expenses. This “Rule of Three” provides a safety net for unexpected equipment repairs, sudden staff turnover, or seasonal dips. You can build this fund incrementally by setting aside a small percentage of your weekly intake. Having this cushion allows you to make calm, strategic decisions rather than reacting out of financial panic during a slow week.

Can salon software really help me save money on credit card fees?

Yes, integrated credit card processing can often reduce your total costs by eliminating the need for separate third-party hardware and reducing manual entry errors. While specific fees vary by provider, integrated systems streamline your reporting and speed up fund availability. This improved efficiency means your money reaches your bank account faster, which is a vital part of how to manage salon cash flow effectively and maintain steady business operations.

How often should I check my salon’s cash flow statement?

You should perform a quick five-minute check of your daily totals every evening and a more detailed review of your cash flow statement once a week. Daily reconciliation prevents small errors from ballooning into large discrepancies. The weekly review allows you to spot trends, such as rising backbar costs or underperforming shifts, before they impact your ability to pay upcoming bills like rent or payroll.

What are the biggest ‘hidden’ expenses in a spa or salon?

The biggest hidden expenses often include backbar waste, untracked petty cash spending, and credit card processing fees. Small, frequent purchases for salon supplies like coffee, towels, or cleaning products can quietly drain your profits if they aren’t logged. Additionally, “frozen cash” tied up in overstocked retail inventory that hasn’t moved in 90 days acts as a major hidden drain on your liquid capital and prevents you from investing in growth.

How do I handle cash flow if I’m a solo chair renter?

Solo chair renters should treat their business like a mini-salon by using specialized Chair/Booth Renter Software to track their individual inflows and outflows. You need to separate your personal and business finances strictly and set aside a fixed percentage of every service for taxes and rent immediately. This disciplined approach ensures you always have the funds ready for your overhead, even if your booking schedule varies from week to week.

What should I do if my salon’s cash flow becomes negative?

If your cash flow becomes negative, the first step is to identify where the money is “leaking” by reviewing your variable expenses. You may need to temporarily reduce inventory orders, adjust staff schedules to match peak hours, or offer high-margin service specials to drive immediate revenue. Focus on collecting deposits for high-ticket services to inject cash into the business quickly. Analyzing your data helps you determine if the issue is a temporary dip or a structural problem.

How can I improve cash flow during the slow post-holiday months?

To improve cash flow during slow periods, use automated marketing to fill empty chairs with loyal clients who haven’t visited recently. You can also promote gift card redemptions or launch specialized membership programs to create recurring, predictable income. Focusing on high-margin treatments, such as scalp treatments or deep conditioning, can increase the average ticket price without significantly increasing your product costs or labor time during these quieter weeks.

Disclaimer

This article is general in nature and may contain errors, please verify all claims with your sales rep